Evergreen Funds: Opportunity or threat for Investors and the Industry?
Within private markets, how should we view the rise of semi-liquid funds, also known as evergreen funds? These structures are appealing because of their apparent flexibility, but they also raise very concrete questions around liquidity, valuation and exit management in an asset class historically built around closed-end vehicles.
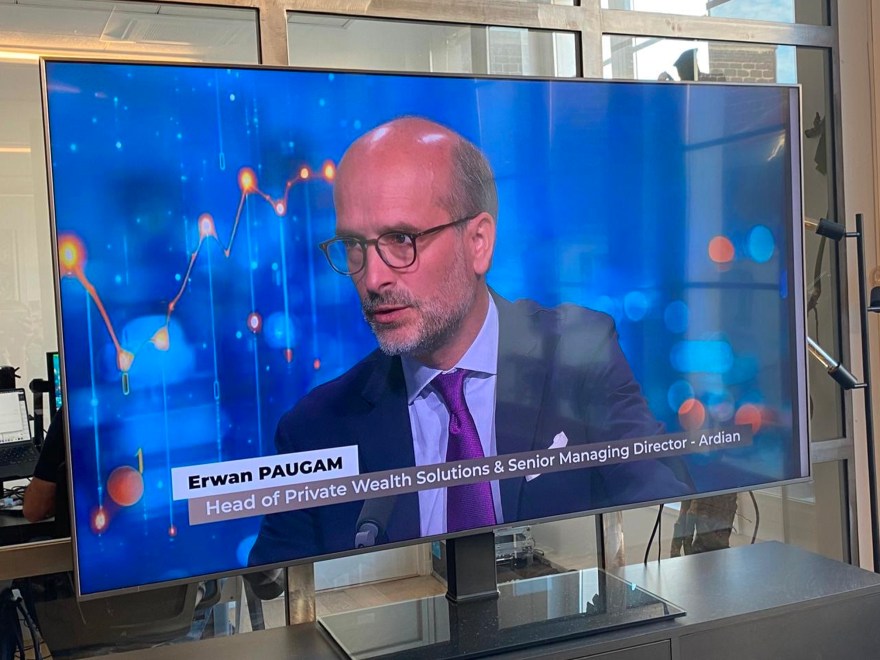
Our clients had the opportunity to hear directly from our experts during a live webinar held on Tuesday 15 September. Discover the main takeaways from this discussion in the article below.
A simplified access to private markets
Evergreen funds differ from closed-end funds in the way they operate: they remain open to subscriptions over time and allow periodic redemptions, subject to certain conditions. They invest in the same universe as closed-end funds — private equity, private debt, infrastructure, real estate or private multi-asset strategies — but they fundamentally change the structure. While a traditional fund operates on a long cycle, with a limited subscription period followed by liquidation at the end of its life, an evergreen fund remains open over time and allows for regular subscriptions.
For investors, this changes the picture considerably:
- no capital calls
- more immediate exposure
- automatic reinvestment of distributions and, under certain conditions
- redemption opportunities at defined intervals
This format responds to a growing demand for simplicity and continuity, and appeals to a broad range of investors: private investors seeking to avoid overly long commitments, family offices looking for flexibility, and institutional investors seeking to smooth their exposure over time.
The evergreen fund landscape
The evergreen fund market has grown rapidly in recent years. More than 600 semi-liquid funds are now listed globally, with growth of 294% since 2020. In the United States, assets under management have also increased sharply, rising by 115% since 2022 according to the data presented during the conference.
This momentum reflects a deeper shift: investors are looking for greater flexibility, while managers are multiplying product formats to meet this demand. Even so, semi-liquid funds still remain a minority compared with closed-end funds.
Liquidity management
In an evergreen fund, liquidity exists — but it is tightly controlled. Redemptions are generally organised through periodic windows, with notice periods, withdrawal caps and sometimes mechanisms for deferral or pro rata treatment.
To meet these requests, the manager relies on several sources:
- cash
- portfolio distributions
- asset sales
- secondary transactions or, in some cases, credit lines depending on the structure of the vehicle
The challenge is a delicate one: too much liquidity in the portfolio can weigh on performance, while too little increases the risk of stress in the event of redemption requests.
Opportunities and challenges
The advantages of evergreen funds are real: they provide easier access to private markets, continuous exposure, automatic reinvestment of cash flows and smoother diversification. For managers, they also open up new distribution and fundraising opportunities. But these benefits come with trade-offs:
- Liquidity may create the illusion of complete flexibility, even though the underlying assets remain structurally illiquid.
- Exit management, regular asset valuation and the risk of procyclical behaviour during periods of stress require strict discipline.
Conclusion
Evergreen funds are not just a passing trend: they make private markets more accessible, more continuous and, at times, more understandable for investors — provided their rules are properly understood.
September 18, 2026